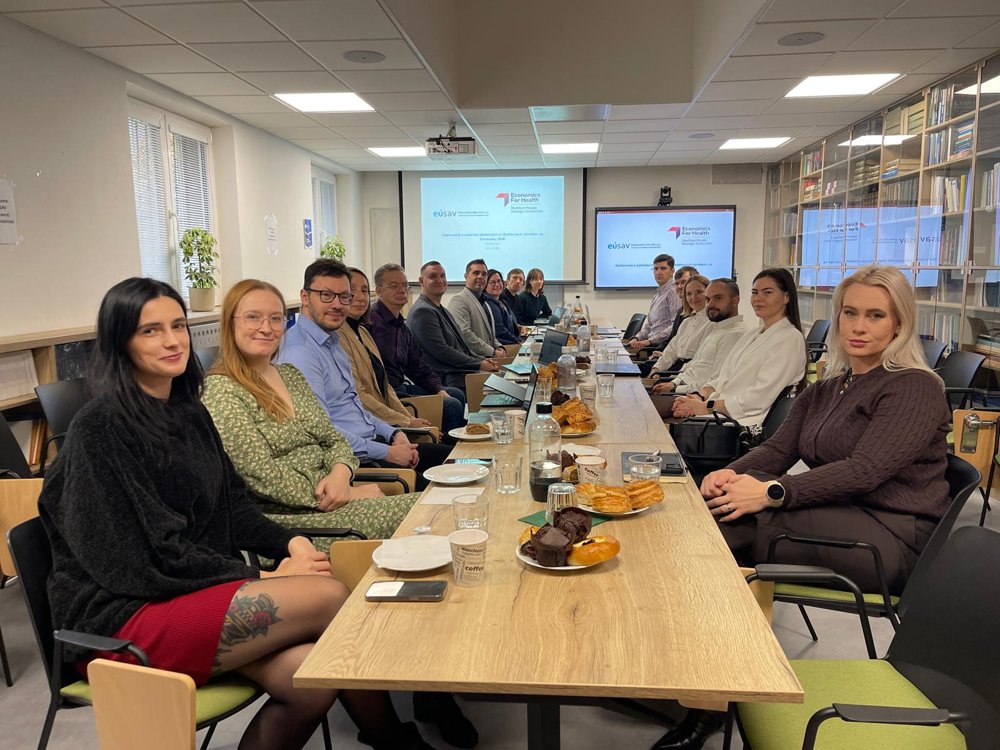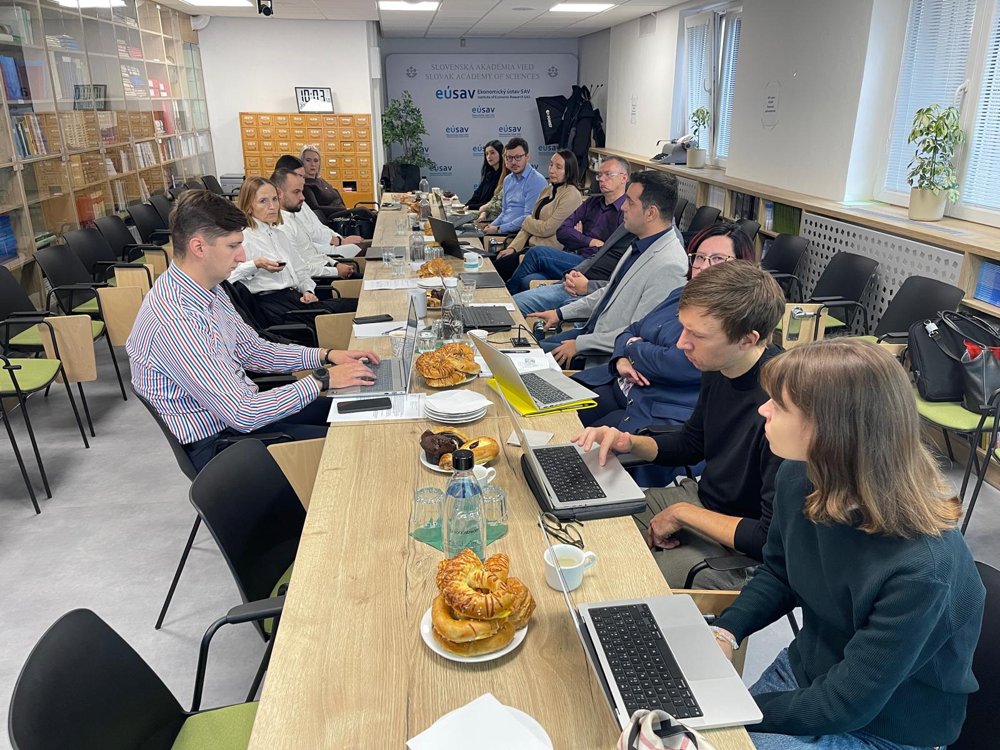
The Institute of Economic Research of the Slovak Academy of Sciences (IER SAS) hosted the round table “Taxation and Consumption of Tobacco and Nicotine Products in Slovakia” on 3 November 2026. It brought together 16 participants from 6 institutions. The event was organised within the project “Economic research to support tobacco tax reform in Slovakia”, funded by the Economics for Health programme at the Johns Hopkins Bloomberg School of Public Health.
The EU context. The programme opened with Hana Ross (Vienna Institute for International Economic Studies), who presented simulations of the proposed revision of the EU Tobacco Taxation Directive. She covered the expected effects on prices, consumption, excise revenues and public health. She also pointed to the high use of e-cigarettes among Slovak teenagers (43.2% among 15–16-year-olds, ESPAD 2024).
How do consumers respond to prices? Ivan Lichner and Filip Ostrihoň (IER SAS) presented the first Slovak estimates of own- and cross-price elasticities for cigarettes, heated tobacco and nicotine pouches. They used district-level cash register data covering period of January 2022 – December 2025. Demand for heated tobacco (−0.46) and nicotine pouches (−0.58) is own-price sensitive, while the response of cigarettes was statistically indistinguishable from zero. Cigarettes and heated tobacco are close substitutes in both directions (cross-elasticities of about +0.48 and +0.49). Cigarettes and pouches show an asymmetric relationship (+1.05 and −0.17).
Do tax increases reach the shelf? Martin Hudcovský and Karol Morvay (IER SAS) presented the first estimates of excise tax pass-through into retail prices. They used almost 9.6 million cash register records for 2022–2025. Cigarette prices rose by about 130% of the tax increase, so the tax was fully passed on and margins grew as well. For heated tobacco, pass-through was about 69%, so about a third of the tax stayed in margins. The new taxes of February 2025 had very different effects: e-cigarettes passed on almost the whole tax (about 99%), while nicotine pouches passed on about 61%. The authors suggest that the size of the tax relative to the product price (about 6% for a disposable e-cigarette versus about 30% for a pouch pack) explains much of the difference.
Slovakia in international comparison. The round table closed with Ivan Lichner presenting the Economics for Health Cigarette Tax Scorecard for Slovakia. The scorecard rates four components of cigarette tax policy on a 5-point scale. Slovakia’s overall score in 2024 was 3.25, above the European regional average (2.7) and the high-income group average (2.6), but below the top performers (4.13). Of the four components, price scored 3, affordability change 2, tax share 4 and tax structure 4.
Key messages for policy makers
• Tax rates should be set jointly across products. Taxing one product alone shifts demand to another instead of reducing total consumption.
• Heated tobacco and nicotine pouches react to price and income and are growing fast, so delay weakens the policy.
• A tax should be assessed by its share of the price, not by its nominal rate. Rates per ml, per gram and per pack are not comparable.
• Heated tobacco passes on less of a tax increase than cigarettes, so the same nominal increase brings a smaller price rise.
• Cross-border coordination matters for a small open market, which fits the current EU Directive revision.